
Trump Accounts opened for contributions on July 4, 2026. Here is how they work, where they fit alongside the accounts you may already own, and, the part most coverage skips, how to raise a child who can handle the handoff.
Key Takeaways
-
New children’s retirement account type launched July 4, 2026
-
Annual contribution limit is $5k per child
-
$5k/yr from birth could grow to roughly $3mn by age 60, tax-free if converted to a Roth in early adulthood
-
The only retirement account a child can fund with no earned income requirement
-
Child would get full control and access at age 18
-
Roth conversion at 18+ makes this excellent
Contribute $5,000 a year to a Trump Account starting the year your child is born, and by their 18th birthday the account could hold roughly $180,000, assuming a hypothetical 7% annual return.
The hard half arrives with the birthday. At 18, the money is legally theirs, with no trustee and no parental override. They need to be ready for the responsibility. Federal law hands your child the keys to a six-figure account the same year they register to vote.
What Exactly Is a Trump Account?
Created under the One Big Beautiful Bill Act of 2025, a Trump Account is a new tax-advantaged savings vehicle for any U.S. child under 18 with a Social Security number. Two features make it unlike anything else on the menu: the child needs no earned income, and the family faces no income limits.
U.S. citizen children born between January 1, 2025 and December 31, 2028 are also eligible for a one-time $1,000 federal seed contribution, but only if a parent or guardian makes the election, either on IRS Form 4547 or through the trumpaccounts.gov portal. There is no cost to make the election through the federal portal. Only one funded account may exist per child.
How to Open One
The account is not automatic; a parent or guardian must make an affirmative election. There are two paths: file IRS Form 4547 (Trump Account Elections) or apply through the online portal at trumpaccounts.gov. Once the election is processed, Treasury coordinates with the account trustee and sends the electing parent or guardian instructions to activate the account through an authentication process. The person who makes the election serves as the responsible party for the account until the child reaches adulthood, selecting investments and handling any rollovers. If your child is eligible for the $1,000 seed contribution, the same election covers enrollment in the pilot program.
The Rules That Matter
-
Contribution cap. $5,000 per child per year from all sources combined, including parents, grandparents, and relatives, indexed for inflation after 2027. An employer can contribute up to $2,500 per employee per year to the Trump Accounts of the employee’s dependents without it counting as income to the employee, though those dollars count toward each child’s $5,000 cap. The federal seed and certain charitable contributions do not.
-
Calendar-year deadline. Contributions must land by December 31.
-
Locked-down investing. Money must sit in broad-based U.S. equity index funds charging 0.10% or less.
-
Locked-up money. Withdrawals are prohibited during the growth period, which generally runs through the end of the year your child turns 17.
-
Gift-tax treatment: read this if you have a gifting program. Under a 2026 IRS safe harbor (Rev. Proc. 2026-25), cash contributions generally qualify for the $19,000 annual gift-tax exclusion with no gift tax return required, but only if the Trump Account contributions are the donor’s only taxable gifts that year and no gift tax return is otherwise required. Families with active gifting programs (annual exclusion gifts to trusts, 529 superfunding, GST allocations) fall outside the safe harbor. For those donors, contributions must be reported on Form 709 as future-interest gifts, which do not qualify for the annual exclusion and instead consume lifetime exemption. If that describes you, coordinate Trump Account contributions with your broader gifting plan before funding.
-
Financial aid treatment. Trump Accounts are treated as retirement assets and excluded from FAFSA asset calculations. One interaction to note: taxable income from Roth conversions during college years flows into the student’s AGI and can reduce need-based aid eligibility, so families expecting aid should sequence conversions accordingly.
The Tax Fine Print and the Roth Endgame
Your contributions go in after-tax and create basis; the contributions come back out tax-free. Everything else does not. The $1,000 seed, any employer dollars, and all investment growth are taxed as ordinary income on the way out. Starting January 1 of the year your child turns 18 (which can arrive before the birthday itself), the account is treated as a traditional IRA: distributions before age 59½ generally trigger income tax on the taxable portion plus a 10% penalty. Standard IRA exceptions apply, including higher education expenses, up to $10,000 for a first home, and certain other hardship categories, which waive the 10% penalty but not the income tax.
Left on autopilot, this is a decent tax-deferred account. One additional move makes it excellent: a Roth conversion during your child’s low-income years.
An example: contribute $5,000 per year at a 7% return, and at 18 the account holds about $182,000, roughly $90,000 of it your contributions (tax-free basis) and $92,000 growth. Converted to a Roth IRA in stages across the college and early-career years, while your child might sit in the 12% bracket, the tax on that growth might run in the neighborhood of $15,000 to $20,000. Ideally, parents pay the conversion tax from outside funds, effectively one more gift, so the full balance keeps working tax-advantaged. What remains can then compound tax-free for four decades. Untouched at the same 7%, it approaches a tax-free $3 million by age 60.
One caution is the kiddie tax: it generally applies through age 17, at age 18 if the child’s earned income does not cover more than half their support, and through age 23 for full-time students meeting the same test. While it applies, conversion income above a small threshold ($2,700 in 2026) is taxed at the parents’ marginal rate, not the child’s. For high-bracket families, the efficient conversion window may not open until the kiddie tax no longer applies, often age 24 for students, so conversions may need to be phased and coordinated year by year.
State tax treatment of Trump Account distributions and Roth conversions varies and is still settling; residents of high-tax states should confirm treatment before executing conversions.
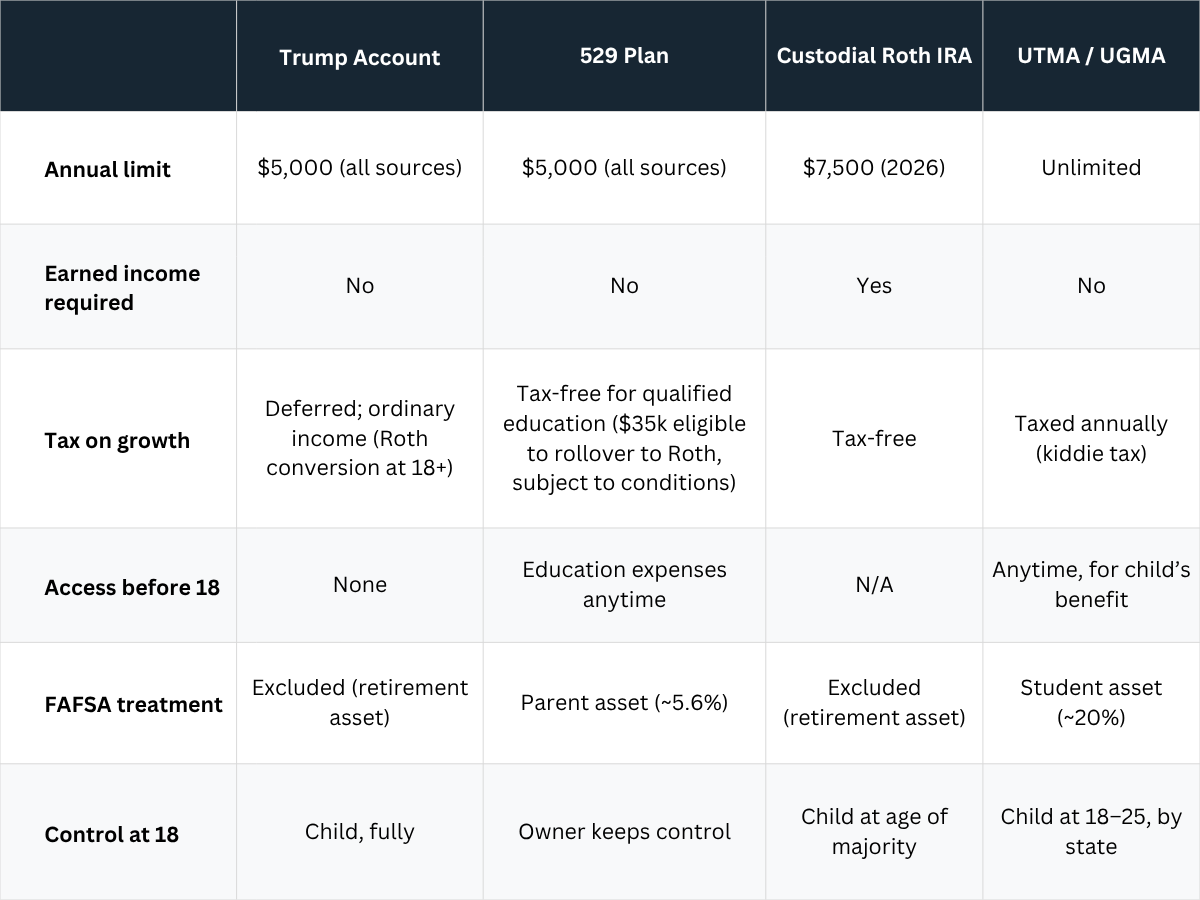
Where It Fits Among 529s, Custodial Roths, and UTMAs
| Trump Account | 529 Plan | Custodial Roth IRA | UTMA / UGMA | |
|---|---|---|---|---|
| Annual limit | $5,000 (all sources) | Up to $19,000 gift exclusion per contributor | $7,500 (2026) | Unlimited |
| Earned income required | No | No | Yes | No |
| Tax on growth | Deferred; ordinary income (Roth conversion at 18+) | Tax-free for qualified education ($35k eligible to rollover to Roth, subject to conditions) | Tax-free | Taxed annually (kiddie tax) |
| Access before 18 | None |
Qualified education expenses anytime, otherwise penalties apply |
Contributions withdrawn tax and penalty free, then taxes and penalties apply | Anytime, for child’s benefit |
| FAFSA treatment | Excluded (retirement asset) | Parent asset (~5.6%) | Excluded (retirement asset) | Student asset (~20%) |
| Control at 18 | Child, fully | Owner keeps control | Child at age of majority | Child at 18–25, by state |
The rankings have not changed for most goals. A 529 remains the better education vehicle, and SECURE 2.0 allows up to $35,000 of leftover 529 money to move into the beneficiary’s Roth IRA over time, subject to conditions (the account must be at least 15 years old, and annual rollovers are capped at the IRA contribution limit and require the beneficiary to have earned income). A custodial Roth is better once your child has a paycheck. The Trump Account’s niche is specific and real: it is the only account that builds retirement-bound wealth from birth, with no earned income and no income limits.
The $180,000 Question: At 18, It Is Their Money
Now for the feature no one prices in. A 529 stays under your control indefinitely. A trust distributes on your schedule. Even a UTMA, in many states, waits until 21 or 25. A Trump Account has no such wrapper: at 18, your child can log in, liquidate, pay taxes and penalties, and spend eighteen years of investing in one weekend. There is no controlled distribution, no trustee, no guardrails.
So the real project is not the account; it is preparing the account holder. Families that move wealth across generations successfully treat the transfer as a graduation the child has trained for, not a reveal. Handled that way, the 18th birthday becomes the moment your child takes over a plan they already understand. You have eighteen years of lead time. Use them.
A Readiness Roadmap, Age by Age
| Ages 5–10
Build the language
|
Ages 11–14
Build ownership
|
Ages 15–17
Build stewardship
|
The Handoff at 18
Turn the plan over
|
|---|---|---|---|
| Normalize money as a household topic. Teach what money is and why it is valuable. An allowance tied to simple jobs, three jars (spend, save, give) and a parent match on whatever lands in the save jar teach the core idea behind the entire account: money left alone grows. Your child does not need to know the balance yet. They need the sentence, “our family puts money away that has a job to do later.” | Show them one statement a year. Explain an index fund in seven words (“you own a piece of 500 companies”) and let them watch a market dip with you, so the first decline they see is a lesson rather than a panic. Make the annual contribution visible, perhaps a birthday ritual. And when the first babysitting or lawn-mowing dollars arrive, consider a small custodial Roth IRA as their hands-on lab: real money, real statements, theirs to watch. | Now, full transparency: the balance, the rules, the taxes, and the plan. Teach why converting to a Roth across their low-income college years could be worth six figures to them over a lifetime. Put them on a real budget with a real paycheck. Then write a one-page plan down together: the account’s job (a retirement engine, not a car fund), what happens at 18, when conversions begin, and who they call before touching anything. At 17, bring them into a meeting with your advisor; a young adult who has met the advisor before the birthday is more likely to act like a steward, not a lottery winner. | Mark the occasion. Let them execute the first Roth conversion themselves, with guidance, so their first act as owner is the disciplined one. Autonomy granted formally is far less likely to be abused than autonomy discovered suddenly. |
And a candid word for parents who doubt readiness: you are allowed to hedge. Keep Trump Account contributions modest and direct the rest into vehicles you control: a 529, a taxable account in your own name earmarked for them, eventually a trust. Money in your name can always be gifted later. Money in their name cannot be taken back.
The Bottom Line
Trump Accounts are a useful new tool for families who have already secured their own retirement: a no-earned-income, no-income-limit head start with a powerful Roth endgame. But the mechanics are the easy half. Fund the account early, invest it simply, plan the conversion, and treat the next eighteen years as the runway to prepare the person receiving the account. Compounding takes care of the money. Only you can prepare the recipient.
If you are weighing where a Trump Account fits alongside your 529s, custodial accounts, and estate plan, we should talk.
Sources
- IRC Section 530A, created by Section 70204 of P.L. 119-21 (One Big Beautiful Bill Act of 2025)
- IRS Notice 2025-68 (December 2025 initial guidance)
- Trump Accounts proposed regulations (March 2026)
- Rev. Proc. 2026-25 (gift tax safe harbor)
- IRS IR-2025-111 (2026 retirement plan limits)
Disclosure: This material is provided for general informational and educational purposes only and does not constitute individualized tax, legal, or investment advice. Trump Account rules are new, and Treasury and IRS guidance continues to evolve; details described here may change. Projections are hypothetical, assume a constant 7% annual return, annual $5,000 contributions, and no fees or taxes during accumulation; they do not reflect any actual investment and are not guarantees of future results. Roth conversion decisions depend on individual facts including income, state of residence, kiddie tax applicability, and financial aid considerations. Gift tax reporting obligations depend on the donor’s overall gifting activity in a given year; consult your tax advisor before contributing. Investing involves risk, including possible loss of principal. Please consult a qualified tax and financial professional about your specific situation. Keystone Global Partners LLC is an SEC-registered investment adviser. Registration does not imply a certain level of skill or training.
