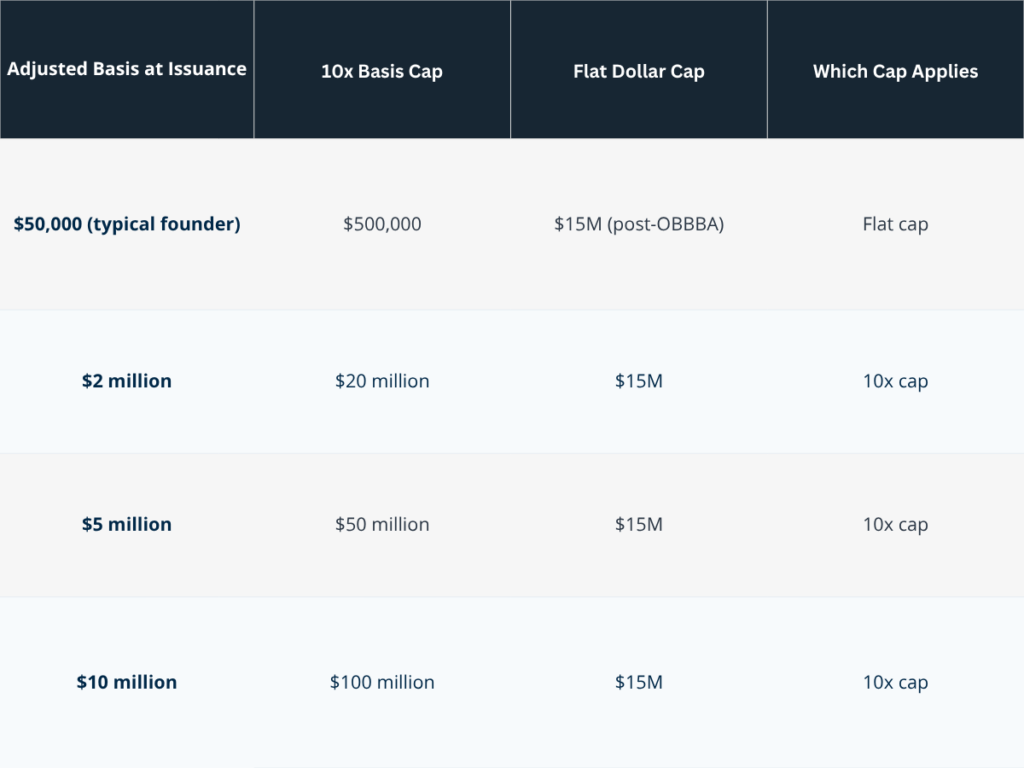
QSBS Packing: The Complete Guide to the 10x Basis Cap
Section 1202 gives qualifying founders a federal tax exclusion of up to $10 million per taxpayer, per issuer. For stock acquired after July 4, 2025, that cap rises to $15
Section 1202 gives qualifying founders a federal tax exclusion of up to $10 million per taxpayer, per issuer. For stock acquired after July 4, 2025, that cap rises to $15
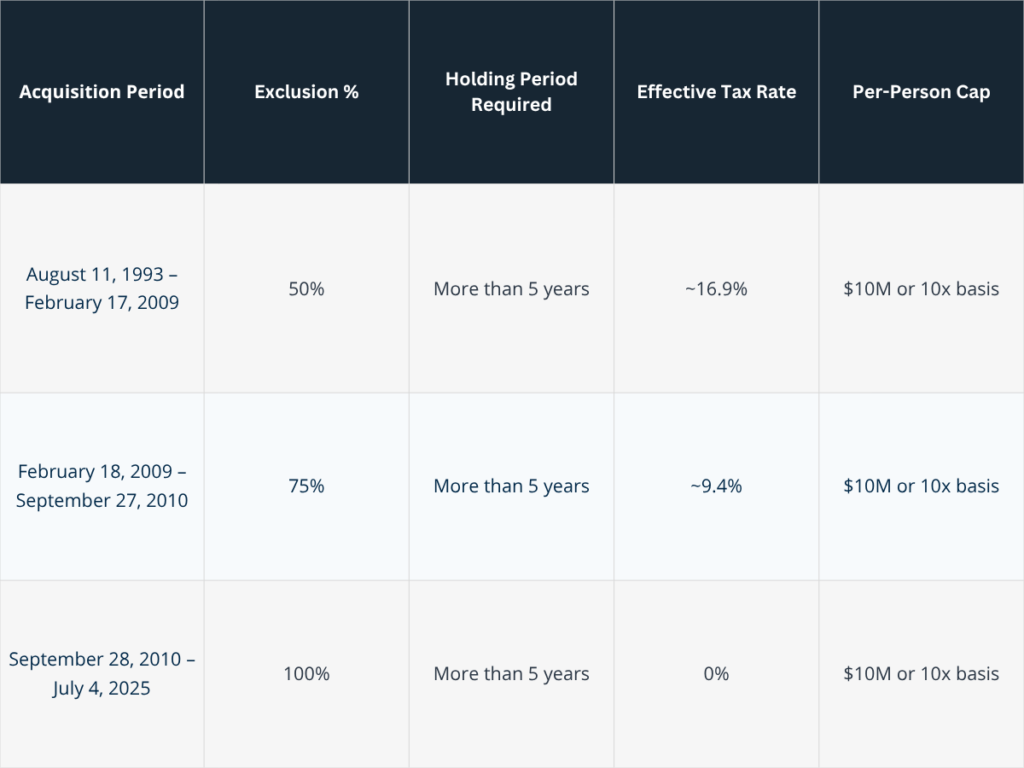
Last updated: November 2026 The Section 1202 tax exclusion for Qualified Small Business Stock (QSBS) has evolved dramatically from its original 1993 introduction to today’s One Big Beautiful Bill Act
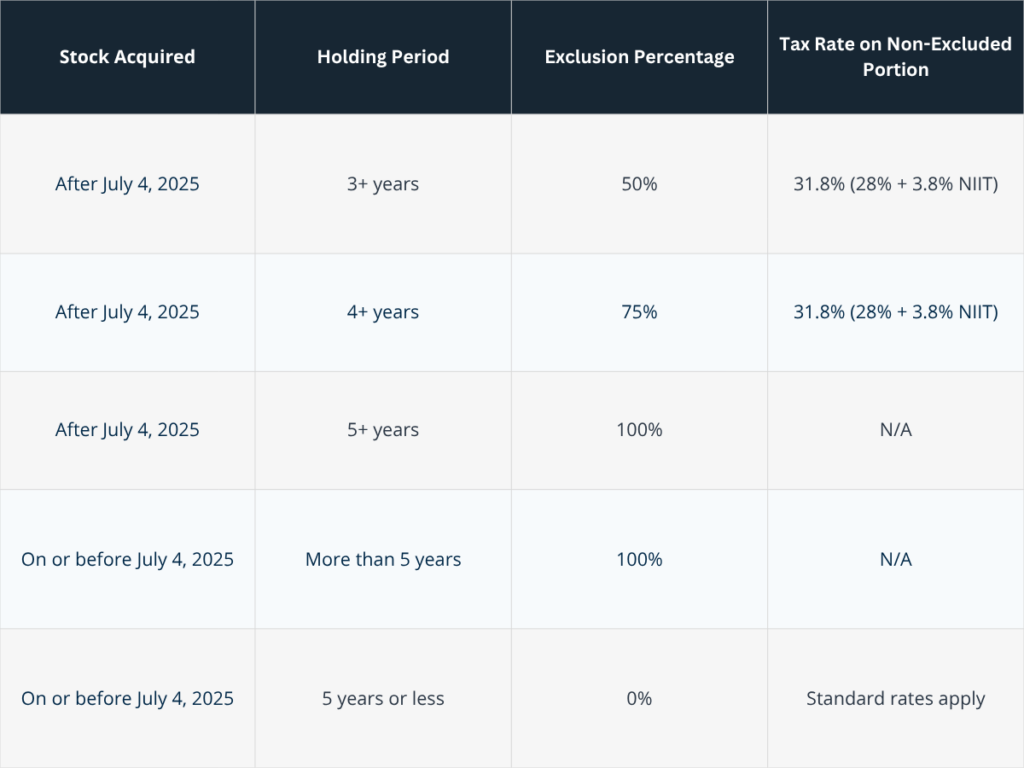
Section 1202 of the Internal Revenue Code offers one of the most powerful tax benefits available to startup founders and early-stage investors: the ability to exclude up to 100% of
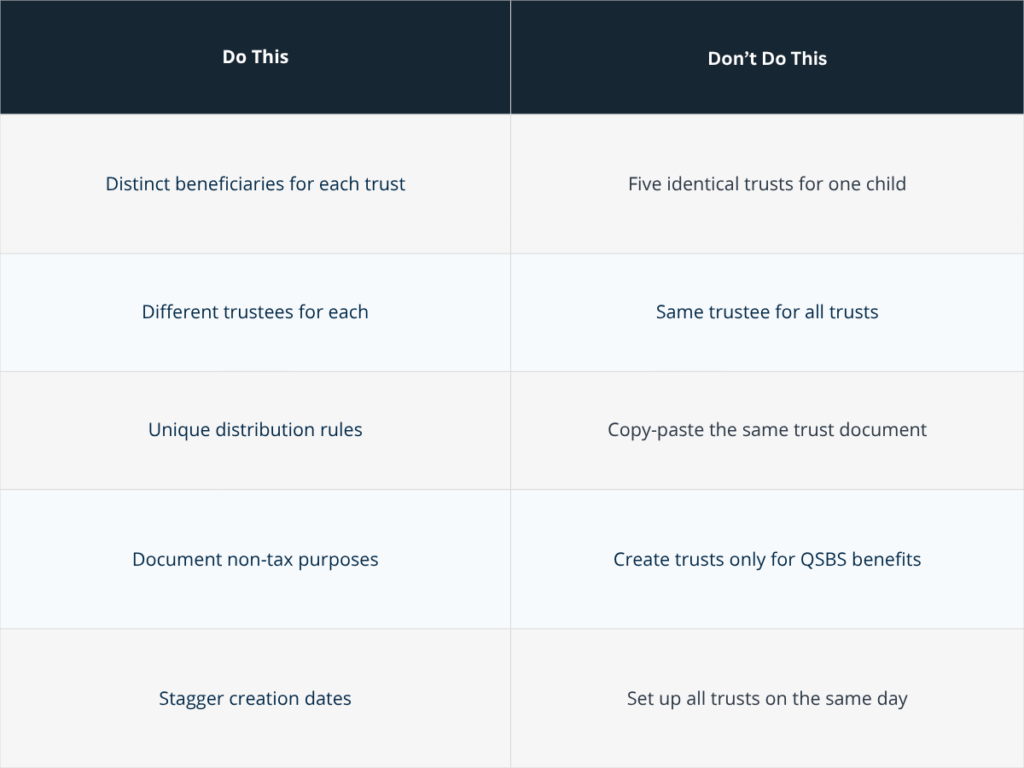
Most founders think QSBS stacking is something you figure out right before selling your company. That’s the fastest way to lose millions to taxes you could have avoided. QSBS stacking
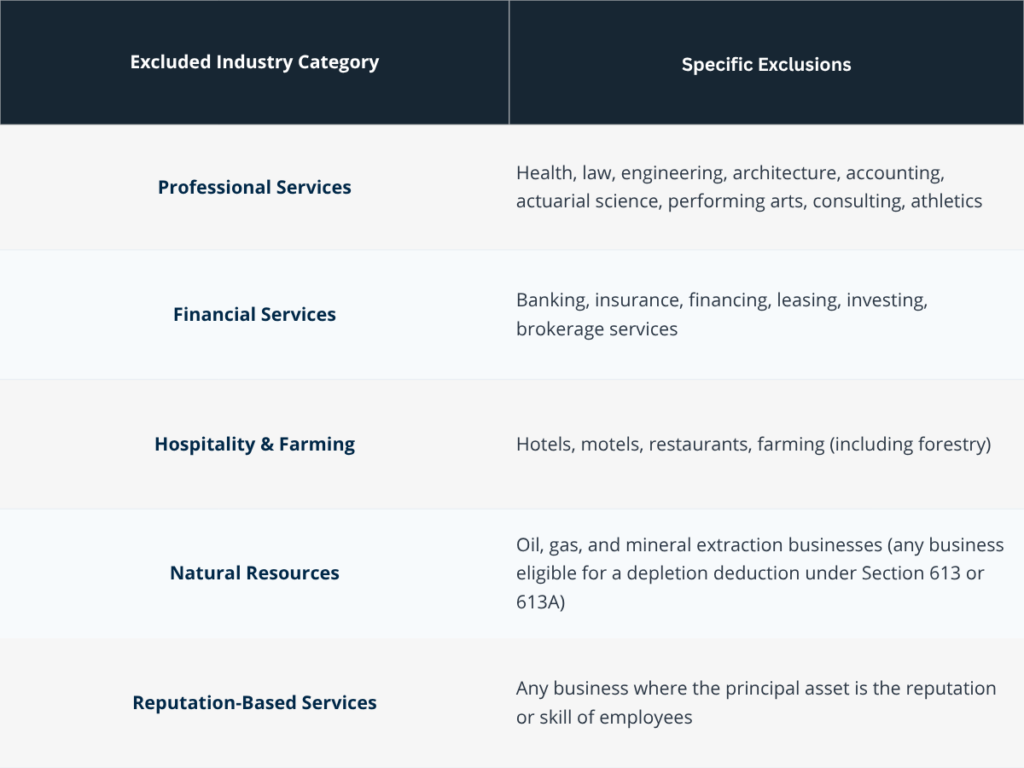
When you’re building a venture-backed tech company, understanding qualified small business stock qualifications can save you millions in federal taxes at exit. Section 1202 of the Internal Revenue Code offers
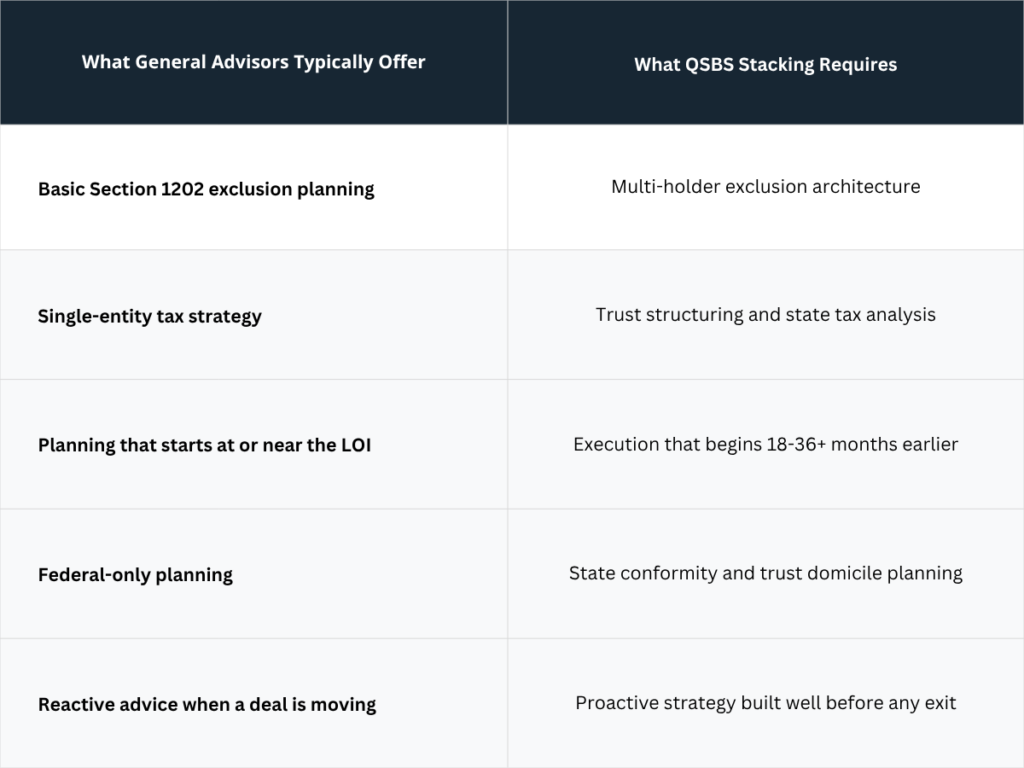
Most founders with qualifying stock know that QSBS offers a federal tax exclusion. But few realize the basic exclusion is just the starting point. Through a strategy called QSBS stacking,
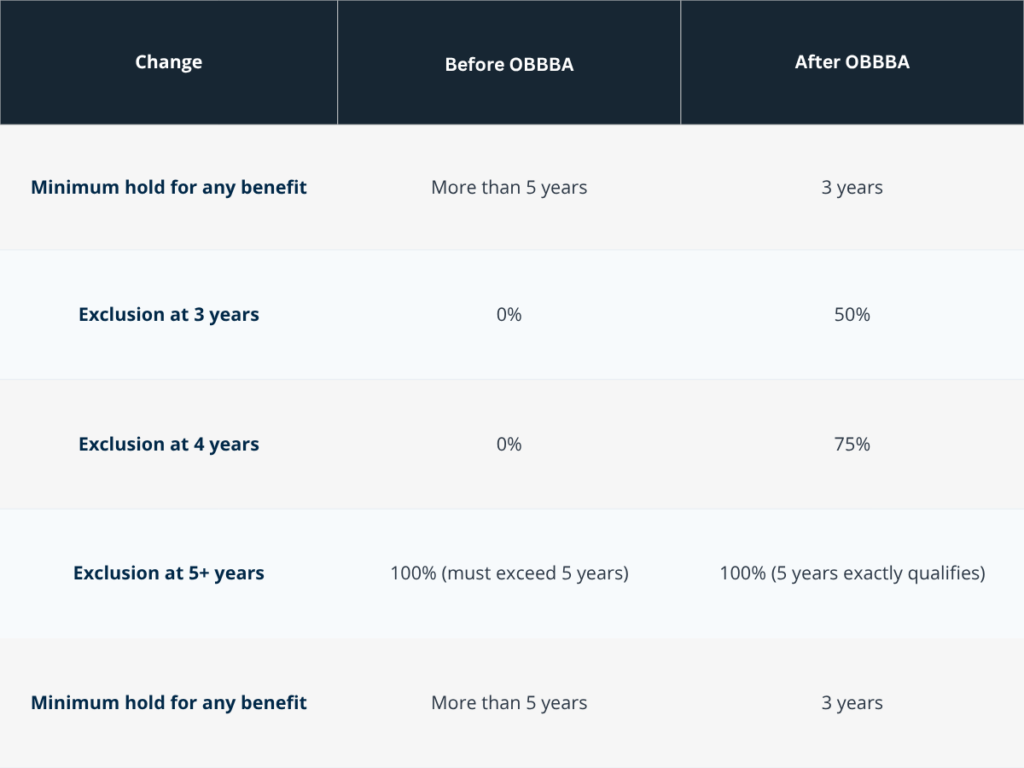
The Qualified Small Business Stock (QSBS) tax exclusion under Section 1202 represents one of the most valuable tax benefits available to startup founders and early-stage investors. Understanding how this exclusion
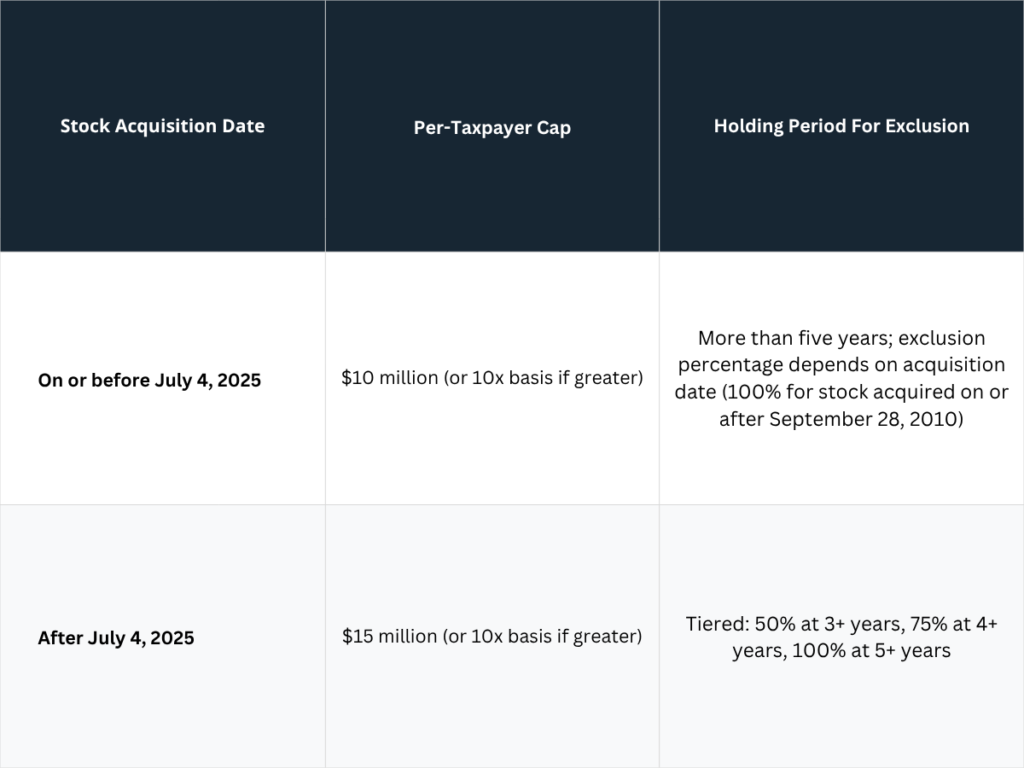
If you hold QSBS acquired on or before July 4, 2025 and have cleared the five-year mark, you are eligible for the exclusion, but only up to $10 million per
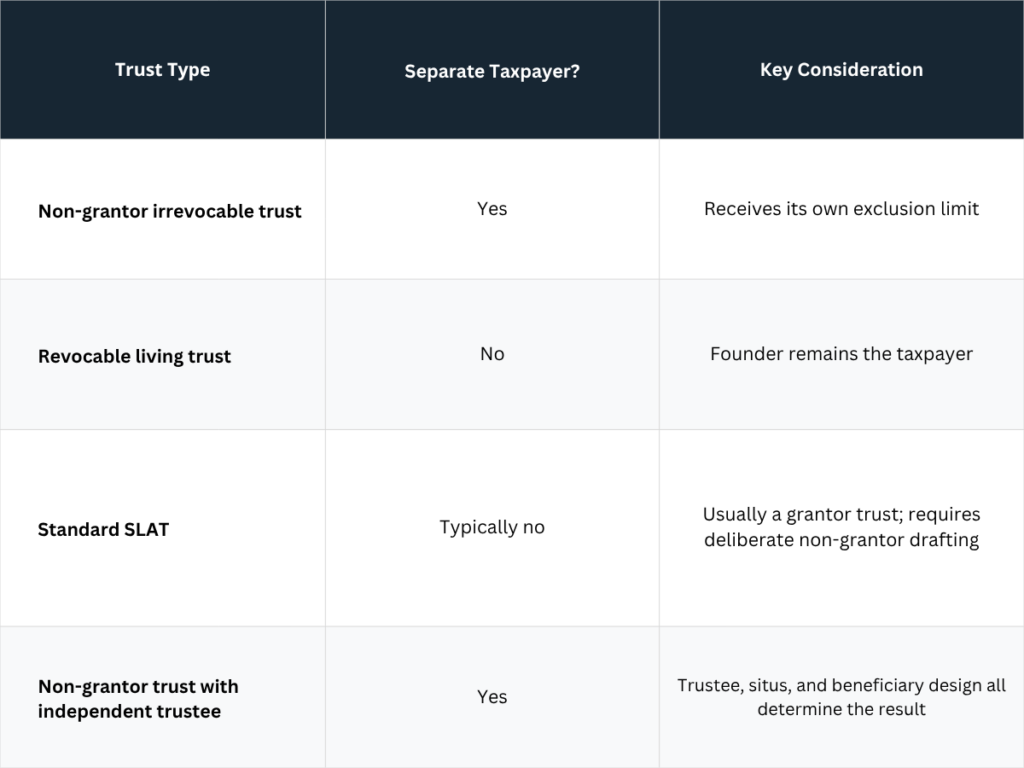
Each properly structured non-grantor trust you fund with QSBS gets its own Section 1202 exclusion cap. Here is what that requires and where founders lose it before closing. This article
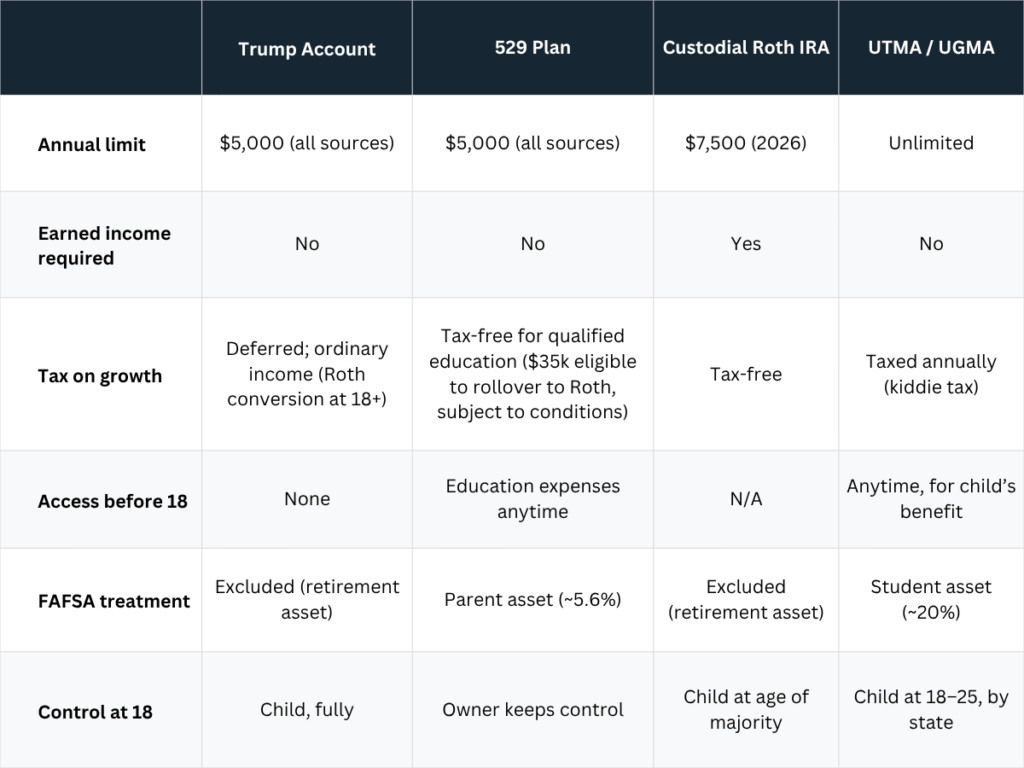
Trump Accounts opened for contributions on July 4, 2026. Here is how they work, where they fit alongside the accounts you may already own, and, the part most coverage skips,
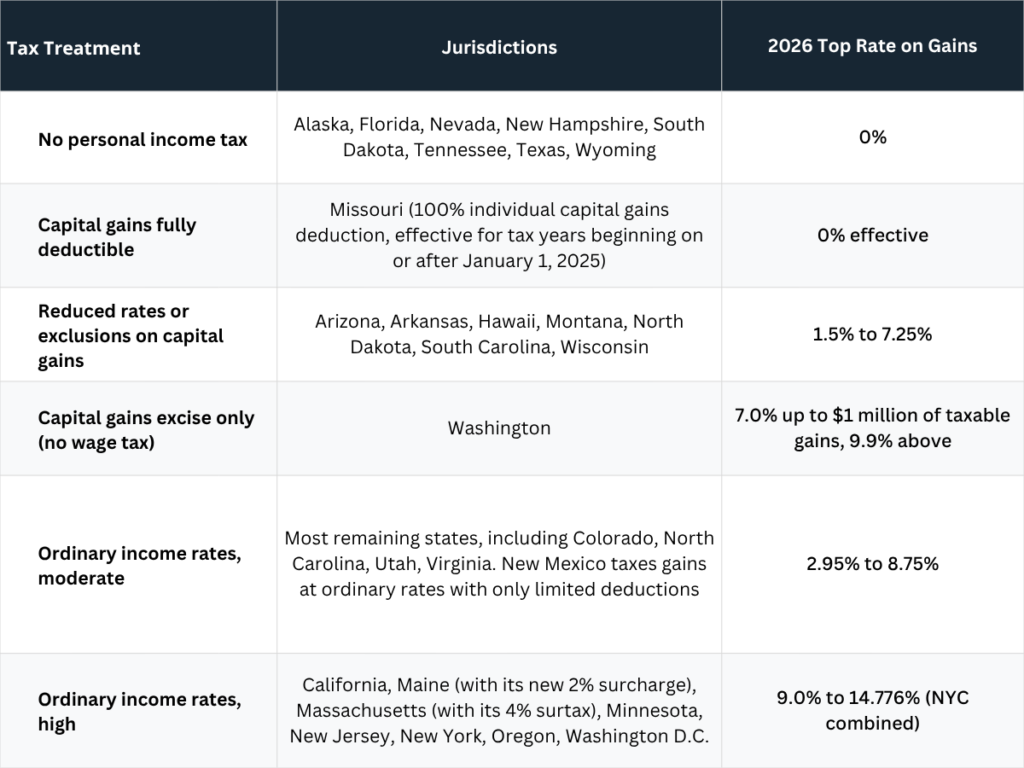
Last updated: September 2026 State capital gains rates in 2026 range from 0% in eight states with no individual income tax to 13.3% in California. On a $50 million taxable

If you’re a founder staring down a $30 million personal exit, here’s a harsh reality: Section 1202’s qualified small business stock (QSBS) exclusion caps out at $10 million per person,